


Build your home in Paraguay with bank financing of up to 30 years.
You do not need all the money up front. We run your financing assessment, help you choose the land, prepare the file for the bank and build with stage disbursements. From the land to the keys, with a single team.
Request your diagnosis · Rates from 6.5% per year · Land + construction in a single loan
We take care of the part everyone puts off: the numbers and the paperwork.
Paraguay has housing loans of up to 30 years, in guaraníes and in dollars, and they can finance the land together with the construction. What usually holds people back is not knowing where to start. That is what our dedicated financing team is for.
- Diagnosis: which line suits you, how much you can finance and how much we can do for you.
- Land screened for the bank: urban plot, clean title, cadastral certificate and taxes up to date.
- Complete file: design, budget and schedule signed by a registered professional, as the bank requires.
- Construction in stages: we coordinate the bank's inspections so disbursements keep pace with progress.
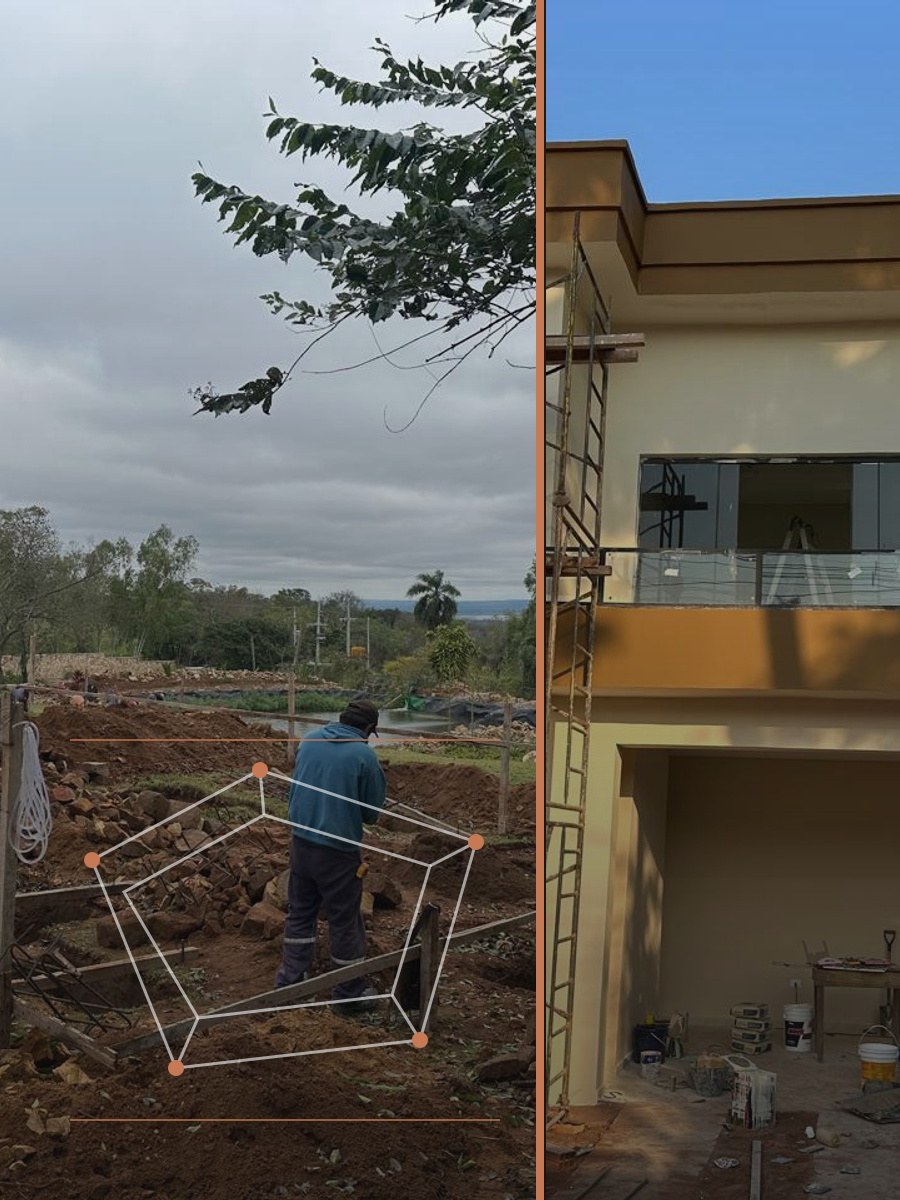
From the first message to the first wall.
A clear path, so you always know which stage you are at.
Assessment
Income profile, residency status, currency and budget. We tell you which products fit and the approximate amount.
Land + design
We choose or evaluate the plot and design a home that fits your budget and what the bank finances.
File to the bank
Documents, appraisal, budget and schedule. We submit to the most suitable bank and follow the review.
Build with disbursements
Once the loan is approved, we build. The bank releases funds by stage and we organise every inspection.
Three products with AFD funds and one alternative with the bank's own funds.
AFD is the public second-tier bank: it lends to banks, finance companies and cooperatives, which in turn lend to you. Each bank sets its final rate and requirements. This is the summary map, with data published in September 2026.
| Che Róga Porã | Primera Vivienda AFD | Mi Casa AFD | Bank's own funds | |
|---|---|---|---|---|
| Who it is for | First home; household income up to 9 minimum wages; Paraguayan ID | First home; household income up to 8 minimum wages | Any creditworthy person; no income cap; up to 2 homes | Homes above the AFD cap or profiles outside the programmes |
| Annual rate | Fixed: 6.5% (up to 6 MW) or 9.9% (6 to 9 MW) | Up to 10.9%, reviewed every 5 years | 11.4% in Gs. or 8.8% to 8.9% in US$ at the major banks | 10% to 15%, reviewed yearly |
| Currency | Guaraníes | Guaraníes | Guaraníes or dollars | Guaraníes or dollars |
| Term | Up to 30 years | Up to 30 years | Up to 27 to 30 years | Up to 10 to 20 years |
| Maximum amount | Gs. 685 to 837 million depending on location and income | Gs. 791 million (260 MW) | Gs. 1,500 million per home | No cap (depends on the bank) |
| Land + construction | Yes, in a single loan | Yes, in a single loan | Yes, in a single loan | Yes; also land only (70% to 100%, up to 10 years) |
Swipe the table sideways to see all columns.
MW = minimum wage (Gs. 3,044,000 since July 2026). Che Róga Porã is a government programme subject to fund availability and prior registration. No AFD product finances land on its own. In every case the instalment cannot exceed 40% of proven household income.
See who lends
Banks authorised by AFD: BNF, Itaú, GNB, Atlas, ueno, Continental, Sudameris, Bancop, Basa, Zeta, Solar, Familiar and Interfisa; finance companies such as Paraguayo-Japonesa, FIC and Tu Financiera; and more than 30 cooperatives (Universitaria, Medalla Milagrosa, Coomecipar, Ñemby and others). In the assessment we tell you which one suits your profile.
What would the instalment be?
Enter the land value (if you do not have it yet), the build cost and your down payment. It is an estimate to guide you; the real simulation is done by our team with the bank.
- Amount to finance
- —
- Minimum household income so the instalment is 40% of income
- —
French amortisation, published nominal annual rate, without insurance or fees (allow 3% to 5% of the loan in initial costs and about 0.5% per year in insurance). Product caps may limit the amount. Indicative estimate, not a loan offer.
To give you a sense: an MU home of about US$ 70,000 financed in dollars at 8.9% over 20 years comes to roughly US$ 625 a month. With the land included (US$ 100,000), between US$ 816 and 893 a month depending on the term.

Real simulation
Let us continue on WhatsApp
We open the chat with your simulation already filled in. With your ID number the financing team moves the enquiry with the bank forward.
Buying is open to all. Financing needs roots in Paraguay.
Here is the path. Any foreigner can buy land or a house with just a passport. For a bank loan, however, banks ask for a Paraguayan ID, residency in the country, income proven in Paraguay with 1 to 3 years of history and a clean Informconf record. In practice it is a 12 to 24 month path, and it is best started with a plan.
- Month 0 Temporary residency, ID card and RUC. An account at a local bank and every payment through it to build a history. If you wish, the plot can already be bought outright or in instalments from the developer.
- Months 1 to 12 Formal income in Paraguay: a job with IPS or your own company with RUC filing VAT every month. A local card paid on time and no arrears.
- Months 12 to 24 With 1 to 2 years of proven income you qualify at the less demanding banks. With permanent residency, Che Róga Porã opens up and the border-strip restriction is lifted.
Under Law 2532/05 on border security, a Brazilian without permanent residency may only own plots classified as urban in San Bernardino, Altos and the whole Central department. Country estates and rural plots are off limits. Before any deposit we request the cadastral certificate and confirm the classification with the notary.
While the bank cannot finance yet, there are options
- Land paid outright or in instalments to the developer (US$ 300 to 500 a month is common in San Bernardino gated communities), with the construction financed once you have 1 to 2 years of local income. The paid-off plot serves as down payment and collateral.
- A loan secured on a property in Brazil (home equity) and a transfer through exchange: the route most used by Brazilians buying in Paraguay.
- Construction paid in stages: the build is paid as it progresses, which already spreads the outlay over 8 to 14 months.
The file the banks ask for.
It varies a little between banks, but this is the base. We go through it with you before submitting.
About you
- Valid ID card (applicant and spouse)
- Proof of address (utility bill)
- No negative records at Informconf
- For Che Róga Porã and Primera Vivienda: declaration of not owning a built property
About your income
- Employees: employment certificate and the last 3 to 6 payslips or IPS slips
- Self-employed: RUC, VAT returns (form 120) for 6 to 12 months, tax compliance certificate and 6 bank statements
- A spouse's income can be added (and, for Primera Vivienda, parents, children or siblings)
- Employment history of 1 to 2 years (employees) or 2 to 5 (self-employed)
About the land and the build
- Title deed or offer letter plus the seller's ID
- Cadastral certificate and property tax up to date
- Appraisal by a bank-approved surveyor (paid by the client)
- Design approved by the municipality
- Budget and physical-financial schedule signed by a registered professional (we prepare this)
Closing costs, no surprises
Between notary, registry, taxes, appraisal, bank fee (1.5% to 2.5% plus VAT) and insurance, allow 2.4% to 4% of the value without a loan and about 4.4% with a loan. From complete file to disbursement usually takes 30 to 60 days.
What almost everyone asks before starting.
Can I finance the land and the construction together?
Yes. Che Róga Porã, Primera Vivienda and Mi Casa AFD cover "land purchase and construction" in a single loan. The bank appraises the land, reviews the design and disburses in stages as the build progresses.
What about just the land, without building now?
No AFD product finances land on its own. Some banks do it with their own funds (for example, 70% of the value over 10 years) and many developers sell in instalments. If the plan is to build, it is better to close land and house in a single loan.
How much do I need to earn?
The instalment has to fit within 40% of proven household income. For Gs. 500 million over 30 years at 9.9%, you need about Gs. 10.9 million of household income. The simulator above gives you the figure for your case.
Do I need a down payment?
Under the AFD lines the bank can finance up to 100% of the appraisal, but the amount is limited by your income and the product cap. Owning the land outright or having a 20% to 30% down payment makes approval much easier.
In guaraníes or in dollars?
In the currency of your income. Dollar rates are lower (8.8% to 10%), but the bank requires that you earn in dollars to avoid currency mismatch.
How long does it take?
The initial assessment is ready in a few days. With a complete file, disbursement usually takes 30 to 60 days, depending on the bank.
I am Brazilian with temporary residency, can I get financing?
You can buy, an urban plot. Financing, in practice, comes after 1 to 2 years of proven income in Paraguay. We build that plan with you: what to do now and what to expect.
What if rates change?
Che Róga Porã is fixed rate; Primera Vivienda is reviewed every 5 years; Mi Casa and own-funds loans are reviewed yearly according to each bank's methodology.
Does MU decide whether the bank approves?
No. MU is neither a bank nor a broker: we present, prepare and accompany. Approval, amount and terms depend on each institution's assessment.
Tell us your case and let’s see how much we can do for you.
With these details our financing team prepares the first simulation with the bank and contacts you by WhatsApp or e-mail.
The home you imagine does not have to wait.
Request your diagnosis and let’s see how much we can do for you. Within a few days you will know which line suits you, how much you can build and what the instalment would be. From the land to the build, we go with you.
Rates, caps and requirements as published by the institutions in September 2026; they change frequently. Simulations are illustrative. Approval, amount and final terms depend exclusively on each institution's credit assessment. MU Construcciones accompanies the process and does not grant loans.